About Us
Independent advisors committed to protecting your assets and helping you build lasting wealth with trusted guidance.

Who we are
At Safe Pacific, we craft personalized financial plans for success-driven Canadians, empowering them to use life insurance as a strategic financial tool. By protecting their greatest assets and helping them achieve lasting financial security, we give our clients peace of mind. We always act in their best interest—because their success is our mission, and their trust is why we love what we do.
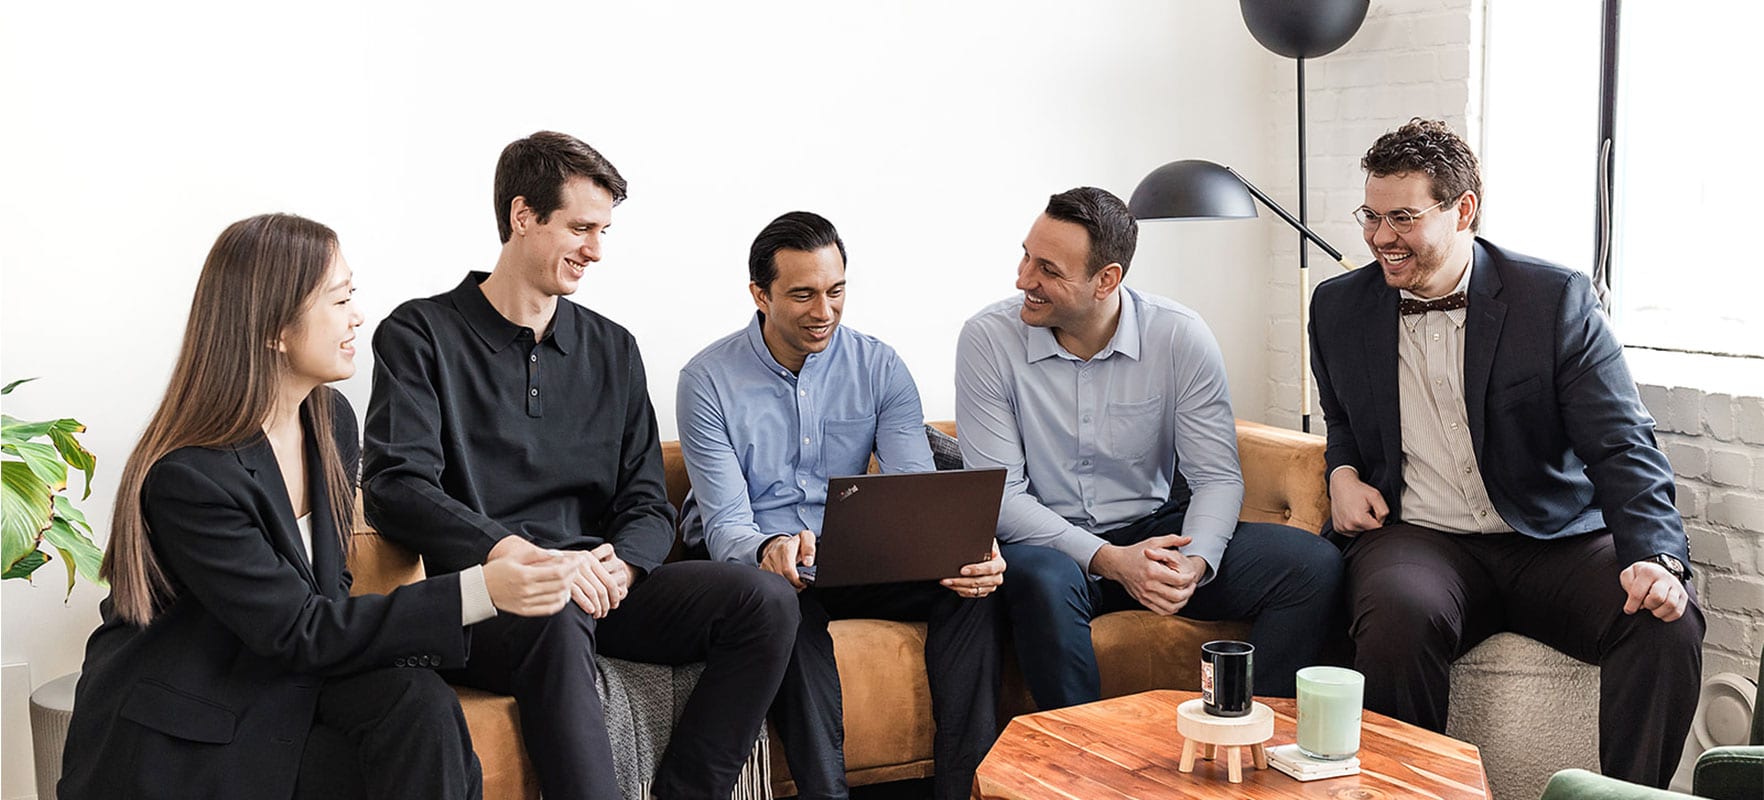
The Safe Pacific Team
Safe Pacific’s dedicated, independent team of experts puts clients first, offering trusted, personalized financial guidance.



Check out our latest insights
Thoughts and insights, updated weekly.
The Trapped-Cash Problem
Executive Summary Surplus profit sitting in a corporate bank or investment account is quietly taxed twice, once on the investment income at close to 50%...
Right-Sizing: Why the Best Strategy Isn't Always the Biggest or the Smallest One
Executive Summary The right strategy is the one correctly sized to what you're actually trying to accomplish, which sometimes means less than what's on the...

The Corporate Asset Your Accountant Isn't Talking About
Executive Summary A properly structured corporate-owned participating whole life policy functions less like insurance and more like a tax-sheltered fixed-income allocation on your corporate balance...
If Something Happened to You Tomorrow… Would Your Plan Actually Work?
Executive Summary: Probably not the way you think, because most business owners have the components of a plan rather than a plan designed to function...
You’re Not Paying Too Much Tax — You Just Don’t Have a Strategy
Executive Summary The tax bill that frustrates incorporated Canadians usually isn't caused by the rates, it's caused by the absence of a coordinated strategy across...
The Silent Risk in Your Portfolio
Executive Summary The silent risk is real estate concentration, where 60% to 80% of a successful Canadian's net worth sits in property that can't be...
Why High Income Isn't the Same as Financial Security
Executive Summary A high income is a resource, not a financial plan, and on its own it can hide real structural fragility behind lifestyle creep,...
Your Corporation Has Accounts You've Probably Never Seen
Executive Summary Your corporation tracks three notional accounts, the Capital Dividend Account, RDTOH, and GRIP, that never appear on a statement but directly determine how...
What Happens After You Reach Out to Safe Pacific?
Executive Summary When you reach out to Safe Pacific, a real person from our team emails you within 24 hours with a link to book...
The Protection Playbook for High-Income Employees
Here's something that surprises a lot of people. Some of the most financially fragile households we see are actually very high-income families. Not because they're...
Whole Life Insurance: The Strategy Most People Miss
Most investment portfolios are built around three pillars. You have equities, you have fixed income, and here in Canada, a lot of people have real...
Why High Earners Are More Vulnerable Than They Think
Most people assume that earning more money makes life simpler. More income, more security, more options. But the uncomfortable truth we see every day is...
Let's Get Social
See more about life at Safe Pacific and watch our myriad videos on Instagram and Youtube.


What if the tax bill on your estate was already paid for?
ㅤ
That’s what a corporate-owned life insurance policy can do. A $500,000 policy pays out tax-free to your holding company, credits the capital dividend account, and lets the corporation distribute those funds tax-free to your family.
ㅤ
No forced sales, no probate delays, and no family panicking over how to pay the CRA.
ㅤ
Comment "MEETING" to book a free call.


Here’s a simplified version of a real client situation.
A Canadian business owner with a holding company and an operating company has built up about $2 million in unrealized capital gains from commercial real estate and a corporate investment portfolio.
When they pass away, the CRA treats those assets as sold at fair market value. Half the $2 million gain is taxable, and at a 50% marginal rate, that’s a $500,000 tax bill due on death.
Comment "MEETING" to book a free call.
Life insurance is often used alongside advanced post-mortem tax strategies.
Loss carryback planning uses losses triggered at death to offset capital gains on your final return. Pipeline planning converts corporate retained earnings into capital gains instead of taxable dividends. An estate freeze locks in today’s value and passes future growth to your family.
Permanent insurance makes all three easier and more reliable, because the CRA wants its money on the next tax filing, and your family receives nothing until it’s paid.
Comment "MEETING" to book a free call.
Own a corporation or holding company? Your estate could pay tax twice.
Once on the capital gains on your shares when you die. Again when the money comes out as taxable dividends to your family.
Corporate-owned life insurance changes that. The death benefit pays the corporation tax-free, credits the capital dividend account, and lets your family receive the funds tax-free. It’s how doctors, dentists, lawyers, and business owners move wealth to the next generation efficiently.
Comment "MEETING" to book a free call.
Capital gains can take a major bite out of your estate, especially if you own real estate, private corporation shares, or other appreciating assets. But there’s a proven, CRA-compliant way to handle it.
Permanent life insurance, whether whole life, universal life, or term 100, pays a guaranteed tax-free death benefit to your beneficiaries or estate. That lump sum can cover the capital gains triggered when you pass.
Your family doesn’t have to sell property, liquidate investments, or give up business shares. The estate passes on intact.
Comment "MEETING" to book a free call.
Without a proper estate plan, the big question for your family becomes simple: how are they going to pay the tax bill?
Often the answer is forced liquidation. Selling real estate, shares, or investments to cover the CRA, and probably not at the best time or the best price. Meanwhile probate is on hold until the taxes are paid.
And when family members have different financial resources and want different things, that stress can turn into real disputes.
Comment "MEETING" to book a free call.
When you pass away, capital gains tax applies to far more than most people realize.
Rental properties, cottages, and vacation homes. Shares in your operating or holding company. Non-registered investments like stocks, ETFs, mutual funds, and GICs. Corporate assets like your office building or corporate investment accounts. Even your principal residence once it passes from your spouse to your kids.
Depending on your estate, that bill can run from thousands to millions, especially if you’re passing on a business or real estate portfolio.
Comment "MEETING" to book a free call.
When you pass away, the CRA assumes you sold all of your capital property at fair market value on the day you died. It’s called a deemed disposition.
No actual sale has to happen. The CRA treats it as if you cashed out your entire portfolio, and the capital gains tax that triggers must be paid before your estate can be settled.
That can mean a massive tax bill, and less for the people you meant to leave it to.
Comment "MEETING" to book a free call.
One of our clients is a physiotherapist, and she told us she can tell exactly who has insurance.
When she recommends coming back every few days, the insured patients say no problem, I’ll be there. The ones without coverage ask how much it’ll cost and whether they can come every two weeks instead.
They’re negotiating on their recovery. For a hundred or a couple hundred dollars a month, critical illness insurance takes that stress away so you can focus on getting better.
Comment "MEETING" to book a free call.
Here’s a critical illness feature some people love and some people skip: return of premium.
If you never make a claim, you can cancel the policy after a set number of years or when it expires and get every dollar of your premiums back tax-free. It works like forced savings. There’s no growth on top, but you get all your money back.
The trade-off? If you take out a policy at 35 and cancel at 55, you’re dropping coverage right when the risk of a heart attack is much higher.
Comment "MEETING" to book a free call.
How much would it actually cost you to be out of work for two years?
That’s the real question behind choosing critical illness coverage. Provincial healthcare covers a lot, but some recoveries take six months and others take two years, and your mortgage, groceries, and utilities keep coming the whole time.
Our rule of thumb is simple: replace one to two years of income. Earn $100,000? Aim for $100,000 to $200,000.
Comment "MEETING" to book a free call.
One in two Canadians will develop cancer in their lifetime. Those aren’t long odds. That’s a coin flip.
Add heart disease and stroke, and the risk gets even harder to ignore. Without coverage, a high income won’t save you. You end up draining retirement savings, selling assets, pausing your business, or taking on debt.
A critical illness plan built around your goals and business structure keeps your financial plan intact when your health isn’t.
Comment "MEETING" to book a free call.
Contact us
Let’s chat. Fill out this form and a member of our team will get back to you within 24hrs on business days.
"*" indicates required fields


